Receipts and payments year-end accounts
For treasurers of charities that aren't companies
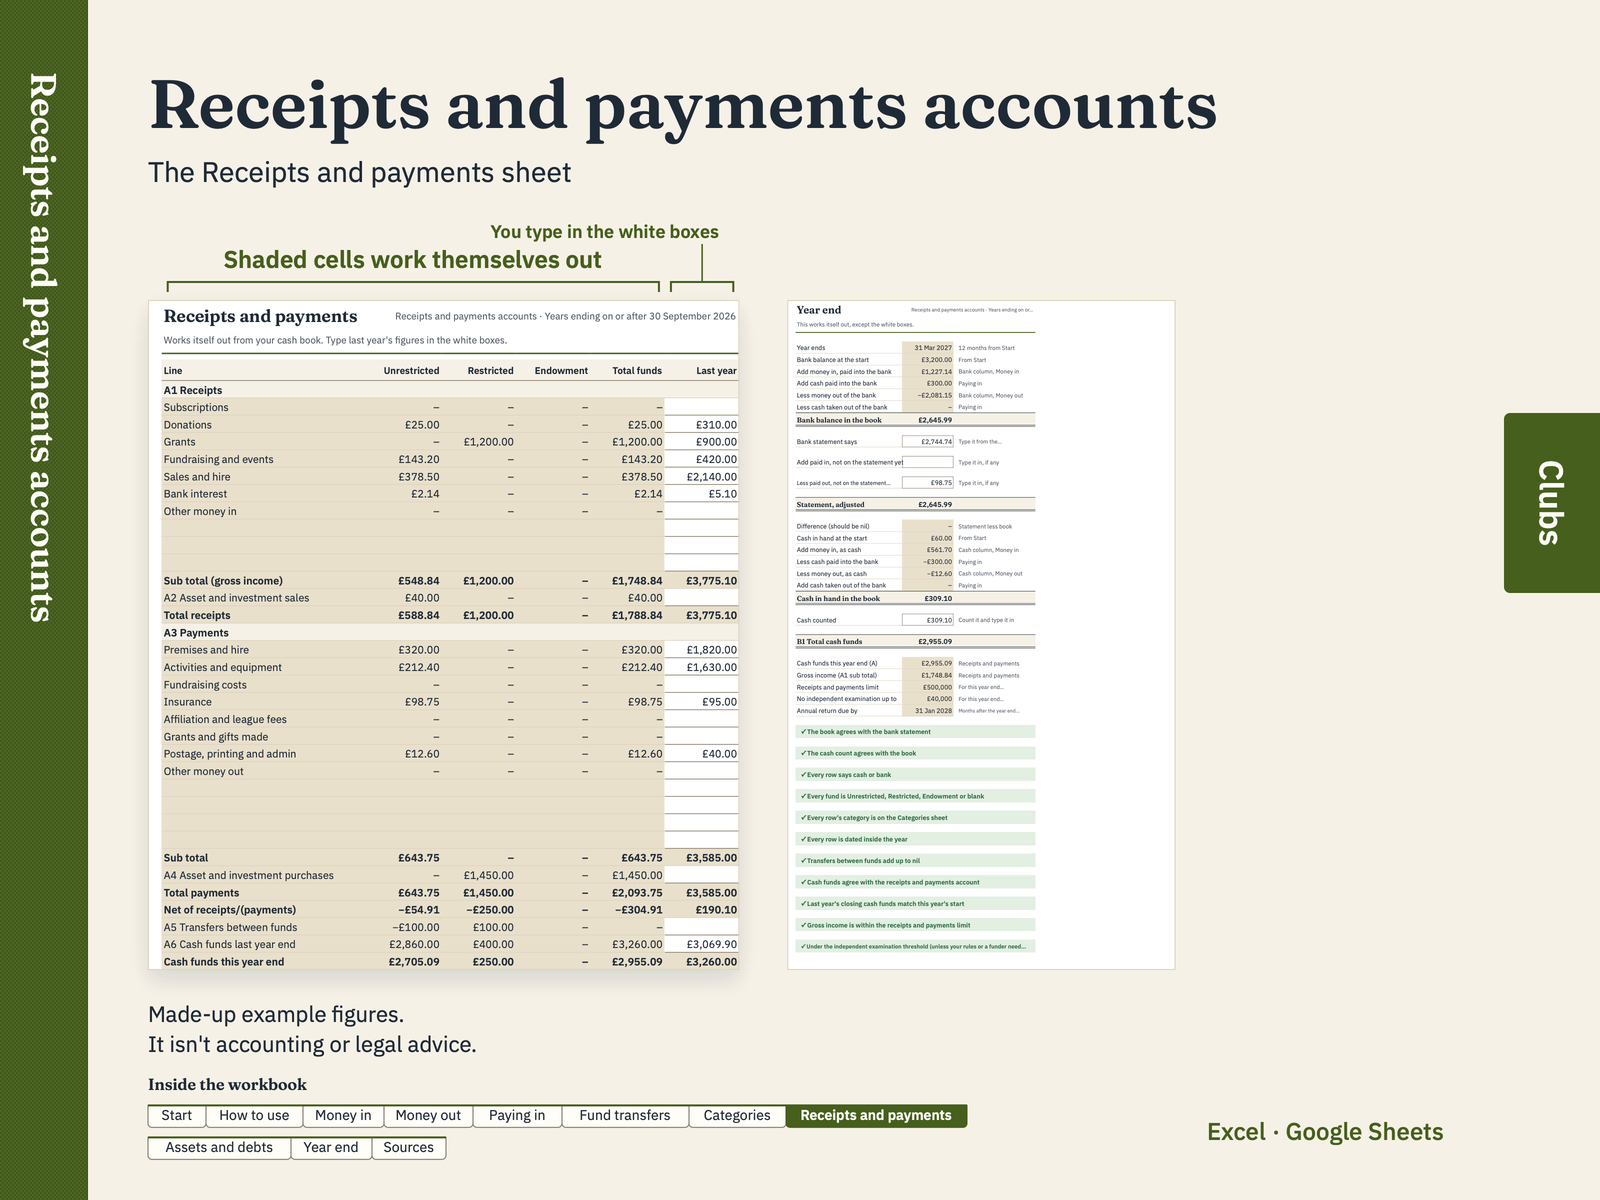
Keep the charity's cash book through the year, with each receipt and payment given a category and a fund. At the year end the workbook lays the totals out the way the Charity Commission's receipts and payments accounts do: receipts, payments, transfers and cash funds by fund, with last year alongside. It uses the new limits: for years ending on or after 30 September 2026, charities that aren't companies can use receipts and payments accounts with gross income up to £500,000.
Inside the workbook
- Money inReceipts, by category and fund
- Money outPayments, by category and fund
- Paying inCash paid into the bank, or drawn out
- Fund transfersMoney moved between funds (A5)
- CategoriesYour headings, and the total for each
- Receipts and paymentsSection A, by fund, with last year
- Assets and debtsSection B: what the charity owns and owes
- Year endBank check, cash funds and the limits
- SourcesEvery rate and rule used, with its GOV.UK link
- Start, How to useA cover with the contents, and plain instructions
Where the figures come from
- Receipts and payments accounts: most gross income, years ending on or after the date below
- Receipts and payments accounts: most gross income, years ending before that date
- No independent examination needed at or under this income, years ending on or after the date below
- No independent examination needed at or under this income, years ending before that date
- The new limits apply to financial years ending on or after
- Annual return due within this many months of the year end
- The Commission's free CC16 template page still describes it as for income of at most
This workbook organises your charity's own figures in the Charity Commission's receipts and payments layout. It isn't accounting or legal advice. Check every figure. Limits link to GOV.UK, checked on 18 October 2026 (Sources tab). Not affiliated with or endorsed by the Charity Commission.